
High-Value Home Insurance for Arizona's Custom Homes and Estates
When your home has outgrown a standard policy, a standard policy becomes a liability. We help homeowners across Paradise Valley, North Scottsdale, Arcadia, and the Biltmore corridor compare high-value home insurance programs built for custom construction, high-end finishes, and the assets that come with them.
Why a Standard Home Policy Falls Short on a Custom Home
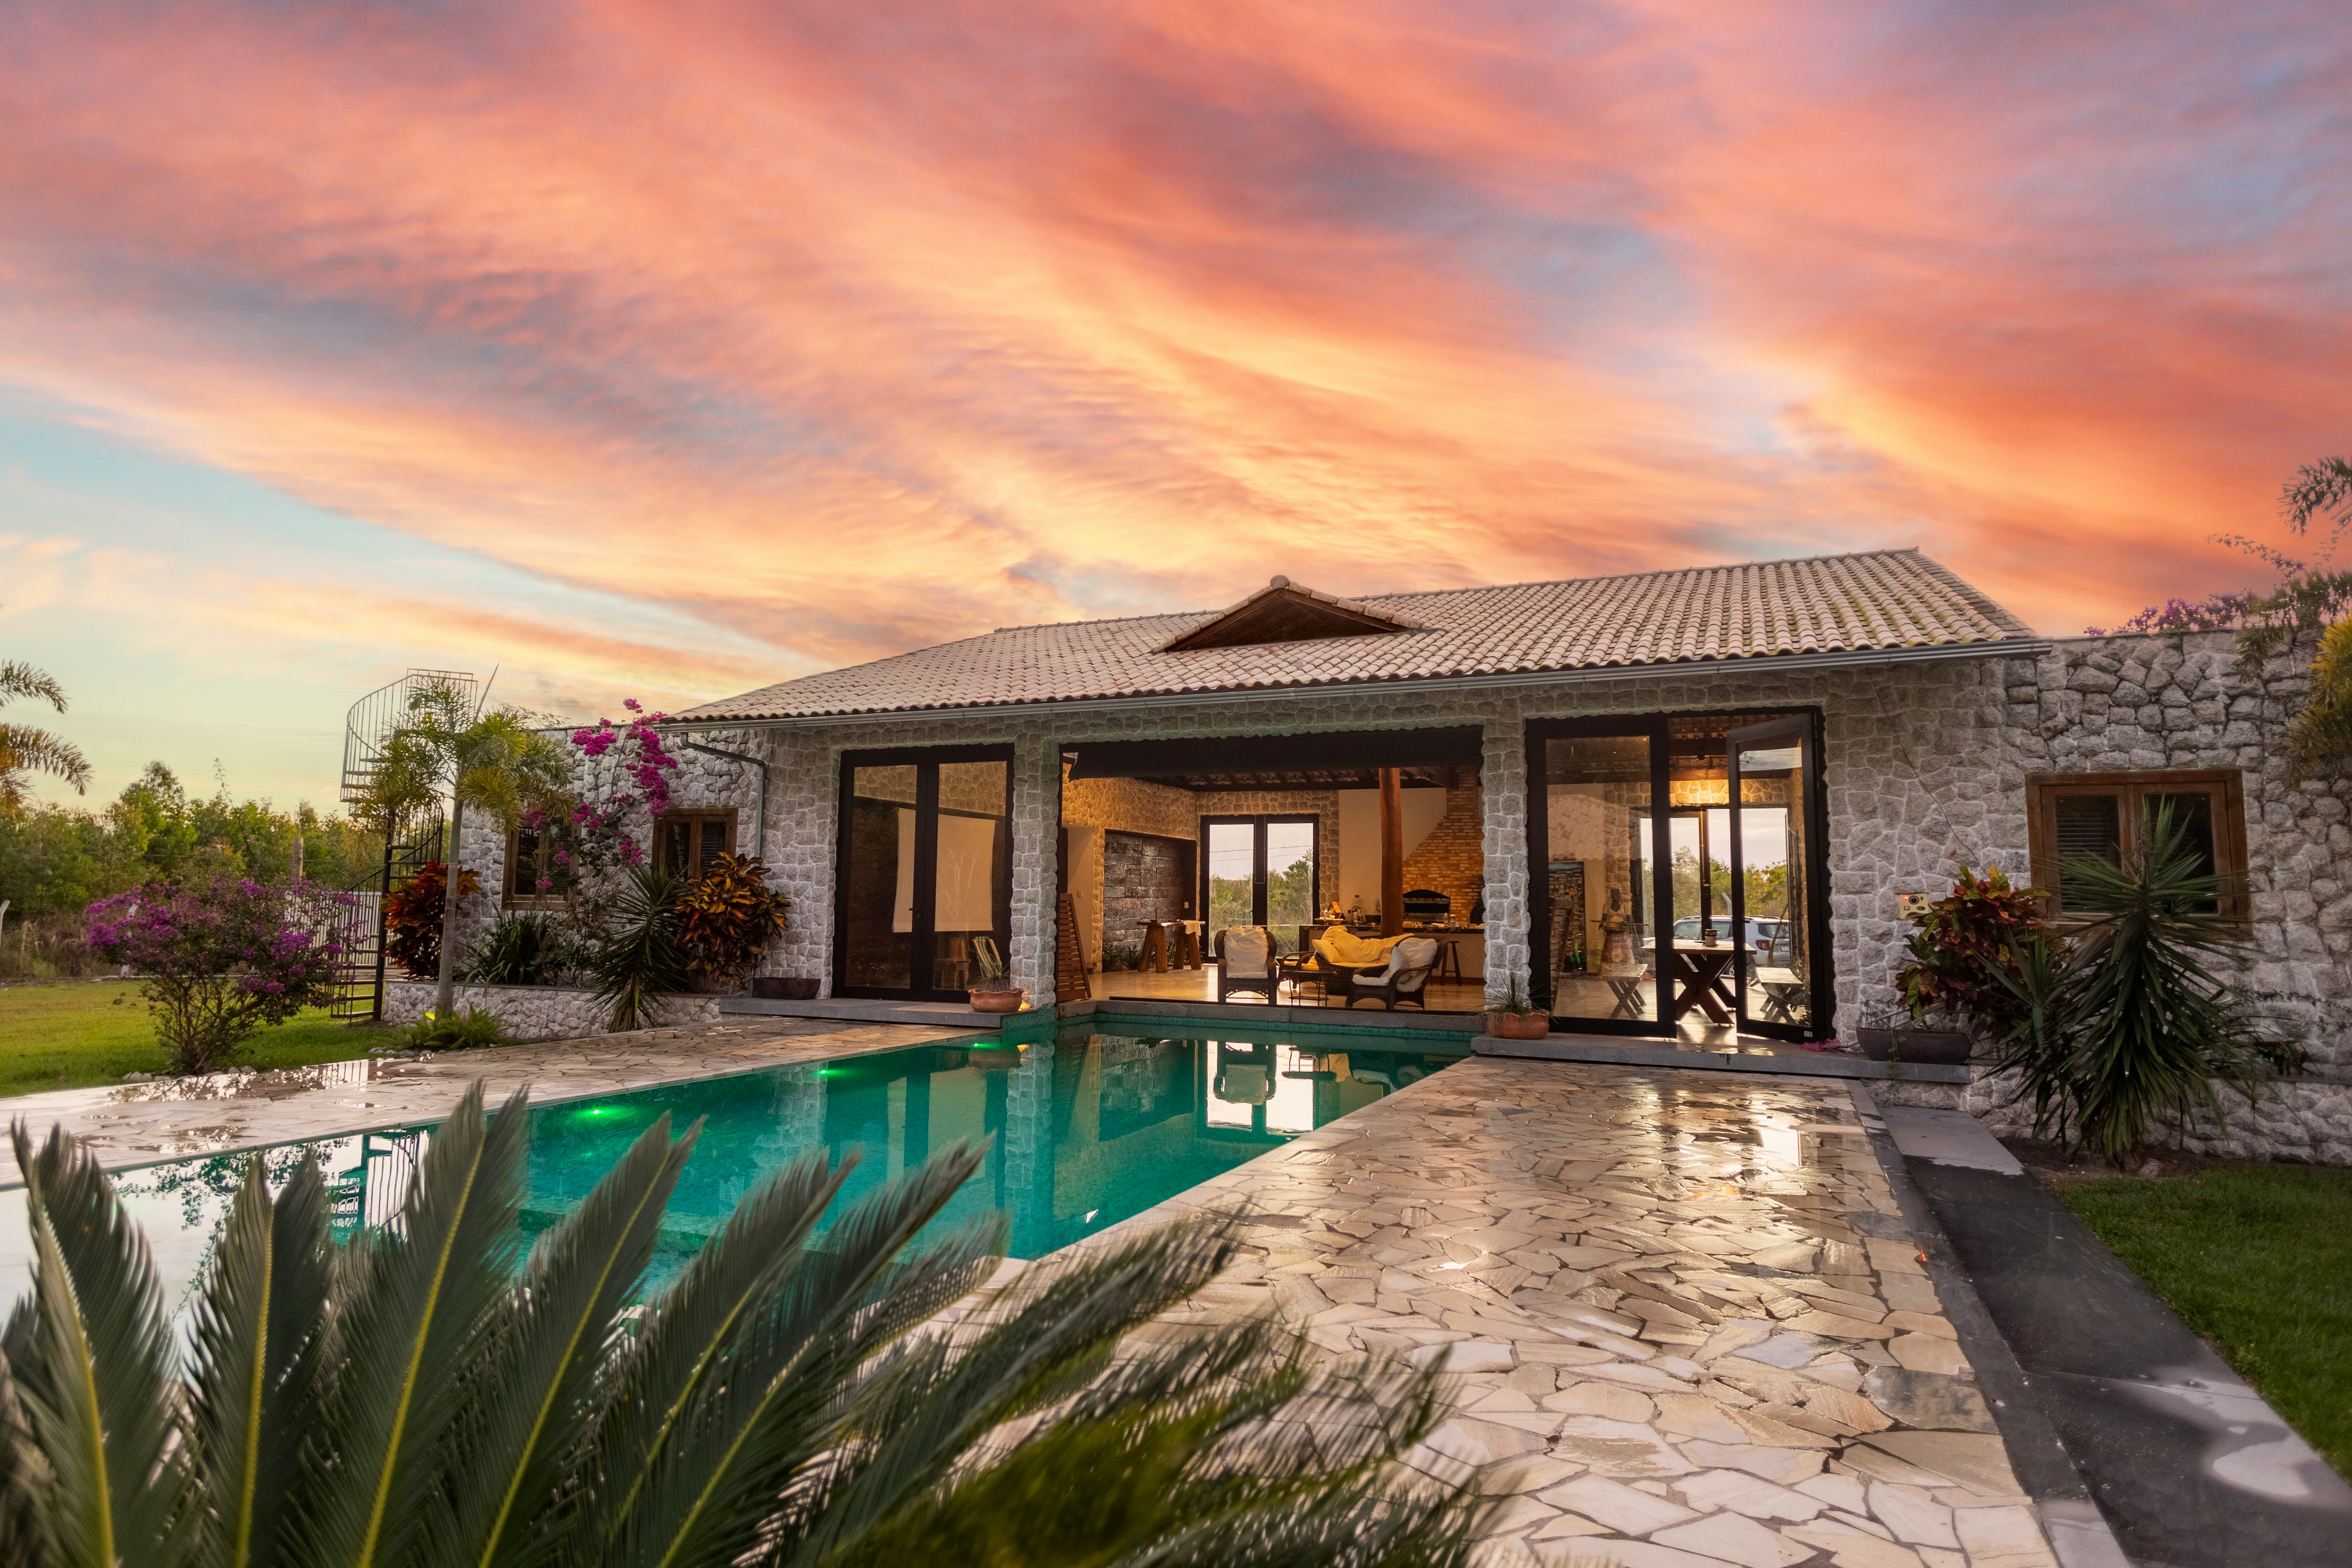
Most standard homeowners policies are written for average construction costs and average contents. If your home features custom desert architecture, high-end finishes, or a rebuild cost that has climbed with Arizona's construction market, a standard policy may leave a significant gap between what you're insured for and what it would actually cost to rebuild. High-value home insurance programs are designed specifically for this gap — with coverage structures, carrier programs, and valuation approaches that reflect what your home is actually worth to rebuild, not what a standard algorithm estimates.
What High-Value Home Insurance Typically Covers — and What to Ask About
High-net-worth home insurance programs differ from standard policies in meaningful ways. When we review coverage options with private-client homeowners, these are the areas we focus on:
- Extended or guaranteed replacement cost. Standard policies cap your dwelling coverage at a fixed limit. High-value programs often offer extended or guaranteed replacement cost options — important when custom finishes, skilled labor, and Arizona's construction costs make a rebuild more expensive than the original purchase price.
- Scheduled personal property. Jewelry, fine art, wine collections, and other valuables are frequently underinsured on a standard policy. Scheduling these items individually gives them dedicated coverage with fewer exclusions.
- Higher liability limits. Homes with pools, guest structures, or significant square footage often warrant higher liability limits than a standard policy provides. We also help clients evaluate whether a personal umbrella policy makes sense alongside their home coverage.
- Secondary and vacation home coverage. If you own a vacation property or additional residence, some high-value programs can extend coverage across multiple locations under a single policy structure.
- Water and weather risk. Arizona's monsoon season brings hail, wind, and flash flooding. Homes in outlying areas near the Tonto National Forest or the McDowell Mountains also face wildfire proximity risk. High-value programs vary in how they handle these exposures — we compare those terms across carriers.
These are coverage options we help you evaluate and compare — not guarantees of what any specific policy will include.
We Shop the Market. We Don't Sell One Company's Product.
R.P. Ryan is an independent, Trusted Choice agency. That means we work with multiple carriers that offer private-client and luxury home programs — comparing coverage structures, replacement-cost approaches, and valuables provisions across the market rather than presenting a single company's pitch. When your home is one of your largest assets, having an independent read on which carrier program fits your situation is worth the conversation.
Independent Access to Multiple High-Value Carriers
R.P. Ryan is an independent, Trusted Choice agency. That means we work with multiple carriers that offer private-client and luxury home programs — comparing coverage structures, replacement-cost approaches, and valuables provisions across the market rather than presenting a single company's pitch. When your home is one of your largest assets, having an independent read on which carrier program fits your situation is worth the conversation.
Coverage Matched to Arizona's Custom Construction Market
Rebuild costs for custom homes in Paradise Valley, Silverleaf, DC Ranch, and Arcadia bear little resemblance to median construction costs. We review replacement-cost coverage with that reality in mind — looking at whether the coverage limit reflects what your home would cost to rebuild with comparable materials and craftsmanship, not what a standard estimator produces.
Your Valuables, Individually Accounted For
A standard policy's personal property coverage is a blanket limit. For clients with jewelry, art, wine, or collections that represent meaningful value, we help evaluate scheduled personal property options across carriers — coverage that sees each item individually rather than folding everything into a single aggregate number.
Common Questions
Common Questions About High-Value Home Insurance in Arizona
What makes high-value home insurance different from a standard homeowners policy?
High-value home insurance programs are designed for homes where standard replacement-cost estimates, blanket personal property limits, and standard liability coverage fall short. They typically offer more flexible dwelling valuation options, the ability to schedule individual valuables, and higher liability limits — structured for homes and households that have outgrown what a standard policy was built to handle.How do I know if my home qualifies for a high-value or private-client program?
Qualification varies by carrier, but many high-value programs are available to homes with rebuild values starting around $500,000 to $750,000, depending on the carrier and the program. The more relevant question is whether your current coverage reflects what your home would actually cost to rebuild — and whether your valuables, liability exposure, and risk profile are accounted for. That's the conversation we start with.Does high-value home insurance cover jewelry, art, and collectibles?
Standard personal property coverage applies blanket limits that often fall short for fine jewelry, art, wine, or collections. High-value programs typically offer scheduled personal property options that cover these items individually. We help clients compare those provisions across carriers and identify where scheduling makes sense.What Arizona-specific risks should high-value homeowners think about?
Monsoon season brings hail, high winds, and flash flooding that can affect even well-built custom homes. Homes in outlying areas near the Tonto National Forest, the McDowell Mountains, or other wildland-urban interface zones also face wildfire proximity exposure. High-value carriers vary in how they underwrite and price these risks — comparing programs with those factors in mind is part of how we approach the review.Can R.P. Ryan cover a second home or vacation property under the same program?
Some high-value and private-client programs allow multiple properties to be covered under a single policy structure, which can simplify administration and ensure consistent coverage terms across locations. Whether that applies to your situation depends on the carriers and programs available to you — we'll compare options when we review your full picture.
Start with a Coverage Review, Not a Sales Pitch
If you own a custom home in Arizona and you're not certain your current policy reflects what it would actually cost to rebuild it, that's the right reason to have a conversation. We compare high-value home insurance programs across multiple carriers, review your replacement-cost coverage, and help you evaluate options for your valuables, liability limits, and any additional properties — without steering you toward one company's product.
Reach out to request a quote or speak with one of our agents directly at (602) 992-9700.